Position size calculator for futures evals
Contracts = risk per trade ÷ (stop in points × point value). With $250 of risk and an 8-point stop on MES ($5 a point), each contract risks $40, so 6 contracts fit. Size from the stop and the dollars, never from how confident the setup feels.
Contracts you can trade
How to pick the risk number
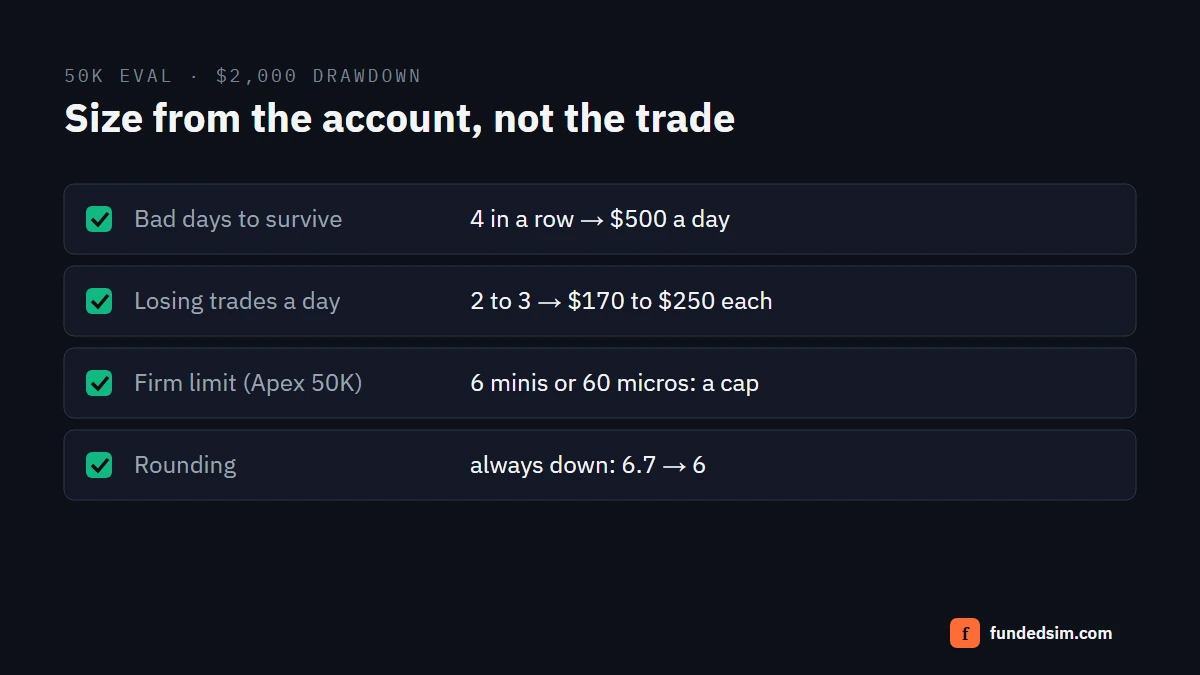
Start from the account, not the trade. On a 50K evaluation with $2,000 of drawdown, a common plan is to survive four bad days in a row, which caps a day at $500. Split that across two or three losing trades and you get a risk per trade between $170 and $250.
The profit target guide walks through the whole plan.
Why the firm limit is a cap, not a target
Every evaluation has a contract limit: 6 minis or 60 micros on an Apex 50K, 5 minis or 50 micros on a Topstep 50K. Put your firm's limit in the last field and the calculator won't suggest more. The limit is the most the firm allows, not the size you should trade.
Rounding always goes down
The calculator rounds down. If the math says 6.7 contracts, you trade 6. Rounding up is how a $250 risk turns into a $280 loss.
Practice the size
Put the size into practice in the simulator and log a week of trades at that size. If the drawdown line keeps getting close, the problem isn't the setup.
Now try it with real trades
The calculator shows the math. The simulator shows what happens when you actually trade the rules day after day.
Open the simulator